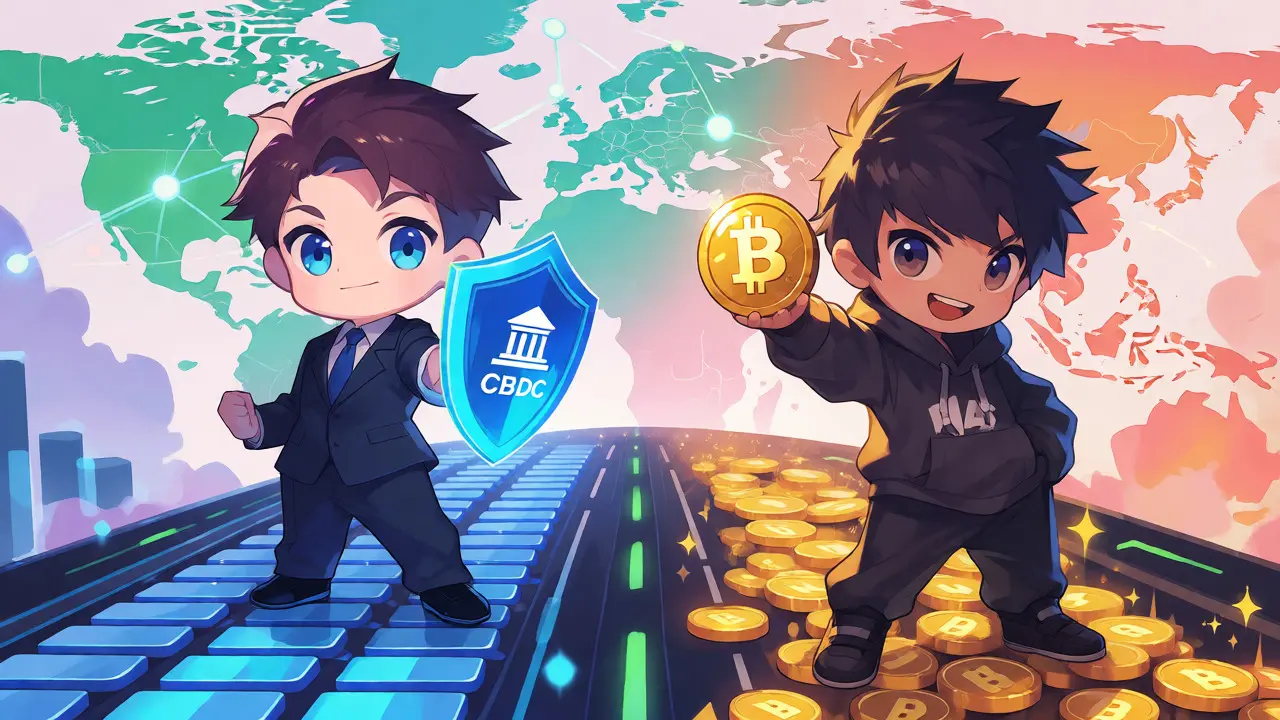
Imagine waking up in Wellington and finding out that your Kiwi dollar exists only as a code on a government server. No cash, no commercial bank deposits-just state-backed digital tokens. This isn't science fiction; it's the trajectory of Central Bank Digital Currency (CBDC) development. While Bitcoin and other private cryptocurrencies have spent years proving they can disrupt finance, central banks aren't sitting idle. They are building their own digital rails, and the collision course between these two worlds is shaping the future of money.
The race is heating up. As of 2025, 134 countries representing 98% of global GDP are actively exploring or developing CBDCs. That’s a massive jump from just 114 countries in 2023. Why the sudden rush? Because governments realized that if they didn't build the digital highway, private crypto companies would pave it themselves-and set the toll rates. But here is the kicker: while CBDCs offer stability and legal tender status, private cryptos offer freedom and speed. Who actually wins this battle depends on what you value more: security or sovereignty.
The State of Play: Where Are We in 2026?
Let's look at the hard numbers. The global landscape has shifted from niche experiments to strategic national priorities. Among the 134 nations engaged, 81 central banks are still in the exploration phase, figuring out the technical and economic implications. Another 69 have moved past theory into pilot and development stages. However, actual deployment remains surprisingly limited. Depending on who you ask, either four countries (the Bahamas, Nigeria, Jamaica, and Zimbabwe) or eleven have fully launched their digital currencies. This gap between ambition and execution tells us something important: building a CBDC is harder than writing a whitepaper for a new altcoin.
The G20 nations show particularly strong commitment. Nineteen of them are exploring CBDCs, and sixteen are already progressing through development or pilot phases. This isn't just about keeping up with tech trends; it's about maintaining monetary control. When major economies like China, India, and the European Union commit resources to digital currencies, they are signaling that the era of purely private digital money might be facing its toughest regulatory challenge yet.
Cross-Border Payments: The Battleground
If there is one area where CBDCs directly threaten private crypto dominance, it's cross-border payments. Traditional international transfers are slow, expensive, and opaque. Private cryptocurrencies promised to fix this by allowing peer-to-peer transfers without intermediaries. But now, central banks are doing it too-with better compliance tools.
Twenty-nine countries are actively participating in cross-border CBDC initiatives. Projects like mBridge and Project Dunbar are testing multi-CBDC platforms to streamline international settlements. These efforts have led to 17 bilateral agreements focused on interoperability and harmonized regulations. The results are tangible: $59 billion worth of cross-border transactions were processed via CBDCs in 2025, a 45% increase from the previous year. This growth positions CBDCs as serious competitors for anyone sending money across borders.
Why does this matter for you? If you're paying for goods overseas or receiving remittances, CBDCs could offer lower fees and faster settlement times compared to traditional banking. And unlike Bitcoin, which faces volatility issues when used for daily transactions, CBDCs maintain stable value because they are pegged to the national currency. For businesses operating internationally, this stability combined with speed is a compelling proposition.
| Feature | CBDC | Private Cryptocurrency |
|---|---|---|
| Legal Status | Legal Tender | Asset/Commodity (varies by jurisdiction) |
| Volatility | Low (Pegged to fiat) | High (Market-driven) |
| Privacy | Regulated Transparency | Pseudonymous/Anonymous options |
| Cross-Border Use | Growing (mBridge, etc.) | Established but volatile |
| Adoption Barrier | Bank integration required | Wallet setup & exchange access |
Regulatory Clarity: A Double-Edged Sword
One of the biggest advantages CBDCs hold over private cryptocurrencies is regulatory clarity. Central banks report that 72% of institutions involved in cross-border initiatives cite reducing transaction costs and settlement times as primary goals. But they also prioritize compliance. Forty-eight percent of participating countries have aligned their Anti-Money Laundering (AML) and Counter-Financing of Terrorism (CFT) regulations to enable smoother CBDC flows. Additionally, 38% of projects are exploring blockchain-based identity verification systems for faster compliance checks.
This regulatory framework provides CBDCs with significant advantages over private cryptocurrencies, which often operate in legal gray areas. If you're a business owner, using a CBDC means you don't have to worry about sudden regulatory crackdowns or tax ambiguities. The rules are clear, and the issuer is the government itself. In contrast, holding Bitcoin or Ethereum often involves navigating a patchwork of inconsistent laws across different jurisdictions.
However, this clarity comes at a cost. The same regulations that provide certainty also limit flexibility. Central banks can freeze assets, impose transaction limits, or even program money to expire. Imagine buying coffee with digital dollars that automatically deduct a small "carbon tax" based on your spending habits. That level of control is possible with CBDCs but difficult to enforce with decentralized private cryptocurrencies.
Technical Implementation and Cybersecurity Risks
Not all CBDCs are created equal. Technical implementation varies significantly across projects. The Reserve Bank of India, for example, has expanded both retail and wholesale CBDCs throughout 2025, incorporating offline functionality and broader participation. This allows users to make payments even without internet connectivity-a crucial feature for financial inclusion in remote areas. Japan's approach through the Bank of Japan demonstrates a more methodical progression, focusing on universal access and user experience optimization since April 2023.
Cybersecurity represents a critical competitive factor. The International Monetary Fund (IMF) specifically addressed cyber resilience in CBDC ecosystems, noting that over 100 central banks view modernizing payment systems as an opportunity to build resilient infrastructure. Modern technologies can potentially offer superior security compared to some private cryptocurrency platforms, which have suffered high-profile hacks and smart contract vulnerabilities.
But CBDCs create vast and complex ecosystems that amplify existing risk exposures. A centralized system presents a single point of failure. If the central bank's servers go down or suffer a sophisticated cyberattack, the entire nation's payment system could halt. Private cryptocurrencies, being decentralized, distribute this risk across thousands of nodes. While individual wallets can be hacked, the network itself rarely fails entirely.
User Adoption and Financial Stability Concerns
Despite the technological promise, user adoption challenges create significant friction. The Atlantic Council identifies several critical obstacles, including the potential for bank runs. If citizens rapidly convert their commercial bank deposits into CBDCs, banks lose the liquidity needed for lending. This could shock interest rates and destabilize the financial system, particularly in countries with fragile economies.
For many people, the convenience of existing digital banking apps (like those offered by ANZ or ASB in New Zealand) is hard to beat. Why switch to a new CBDC wallet if the current system works fine? Private cryptocurrencies face a similar hurdle but appeal to a different demographic: those dissatisfied with the traditional system altogether. They value censorship resistance and independence from government monetary policy.
Interoperability with existing systems provides CBDCs with a competitive edge here. Research indicates that 26 central banks report interoperability with private digital payment systems as a major focus. This integration capability allows CBDCs to leverage existing financial infrastructure while maintaining regulatory compliance. Users might not even realize they are using a CBDC-it could simply appear as a new option within their familiar banking app.
National Security and Geopolitical Implications
The rise of CBDCs isn't just an economic story; it's a geopolitical one. New payment systems generate externalities impacting citizens' daily lives while potentially jeopardizing national security objectives. CBDCs can limit the United States' ability to track cross-border flows and enforce sanctions, especially if rival powers adopt competing digital standards. The absence of US leadership in standards setting could have long-term consequences for global financial influence.
Private cryptocurrencies face similar concerns but operate outside direct government control. This creates different risk profiles. Governments might restrict private crypto usage to prevent capital flight, while simultaneously promoting their own CBDCs to retain control over monetary policy. For users in countries with unstable currencies, private crypto often serves as a hedge against inflation and government mismanagement. CBDCs, being tied to the national currency, cannot offer this escape hatch.
The Future: Coexistence or Domination?
So, who wins? It's unlikely to be a zero-sum game. Current development patterns suggest successful CBDC implementations will focus on specific use cases where government backing provides clear advantages, such as cross-border payments, financial inclusion, and regulatory compliance. Private cryptocurrencies may maintain advantages in areas requiring censorship resistance, decentralized governance, and independence from government monetary policy.
The coexistence and competition between these systems will likely define the digital currency landscape throughout the remainder of the 2020s. Success will be determined by user adoption, regulatory clarity, technical performance, and institutional support across different geographic markets. For you, the consumer, this means more choices-but also more complexity. You'll need to decide whether you trust the state to manage your digital money or prefer the wild west of decentralized networks.
What is the main difference between a CBDC and Bitcoin?
The core difference lies in issuance and control. A CBDC is issued by a central bank and is legal tender, meaning it must be accepted for debts within the country. It is centralized and regulated. Bitcoin is a decentralized asset issued by no single entity, relying on consensus mechanisms rather than government decree. Bitcoin is not legal tender in most countries and its value fluctuates freely.
Will CBDCs replace physical cash entirely?
Not necessarily. Most central banks design CBDCs to coexist with physical cash. Cash offers anonymity and works without electricity or internet, features that are valuable during emergencies or for privacy-conscious users. However, the circulation of physical cash may decline significantly as digital payments become more convenient and widespread.
How do CBDCs affect privacy compared to private crypto?
CBDCs generally offer less privacy than private cryptocurrencies. Since they are linked to verified identities for anti-money laundering purposes, transactions are transparent to the issuing authority. Private cryptocurrencies like Monero offer higher levels of anonymity, though public blockchains like Bitcoin provide pseudonymity, which can still be traced with advanced analytics.
Can I lose my money if a CBDC system fails?
In theory, yes, due to systemic risks like cyberattacks or technical failures. Unlike bank deposits, which are often insured up to a certain amount, CBDC holdings are direct liabilities of the central bank. While central banks have robust disaster recovery plans, a catastrophic failure of the digital infrastructure could temporarily lock users out of their funds.
Are CBDCs good for cross-border payments?
Yes, they are designed to improve cross-border efficiency. Initiatives like mBridge allow different national CBDCs to interact directly, reducing the need for correspondent banks and lowering fees. This makes international transfers faster and cheaper compared to traditional SWIFT transfers, though private stablecoins currently compete aggressively in this space.