Imagine buying a house without waiting 60 days for closing, without paying hefty fees to three different middlemen, and with a title deed that can’t be forged. Sounds like science fiction? It’s not. Blockchain real estate transactions are turning this scenario into reality, shifting property deals from paper-heavy nightmares to streamlined digital processes. If you’ve ever felt the pain of traditional property transfers-endless paperwork, slow bank wires, and opaque title searches-you’re exactly who needs to understand how distributed ledger technology is reshaping the market.
The Core Problem with Traditional Property Transfers
Let’s be honest: buying property today is slow, expensive, and prone to human error. In most jurisdictions, a standard residential transaction takes between 30 and 60 days. Why? Because it involves a chain of intermediaries. You have title companies verifying history, escrow agents holding money, lawyers drafting documents, and banks processing wires that take days to clear, especially across borders.
This system relies on trust in institutions rather than code. If a title search misses a lien, or if a wire transfer gets delayed due to banking hours, your deal stalls. The National Association of REALTORS has acknowledged that while these systems work, they are inefficient. Blockchain offers a way out by replacing institutional trust with cryptographic proof. Instead of trusting a clerk at the county recorder’s office, you trust the network’s consensus mechanism.
How Distributed Ledgers Work for Property
At its heart, blockchain is a shared database that no single person controls. When applied to real estate, every change in ownership, every lien placed, and every payment made is recorded as a "block" added to a chain. This creates an immutable record. Once a transaction is written to the ledger, it cannot be altered or deleted without changing every subsequent block, which requires massive computational power and network agreement.
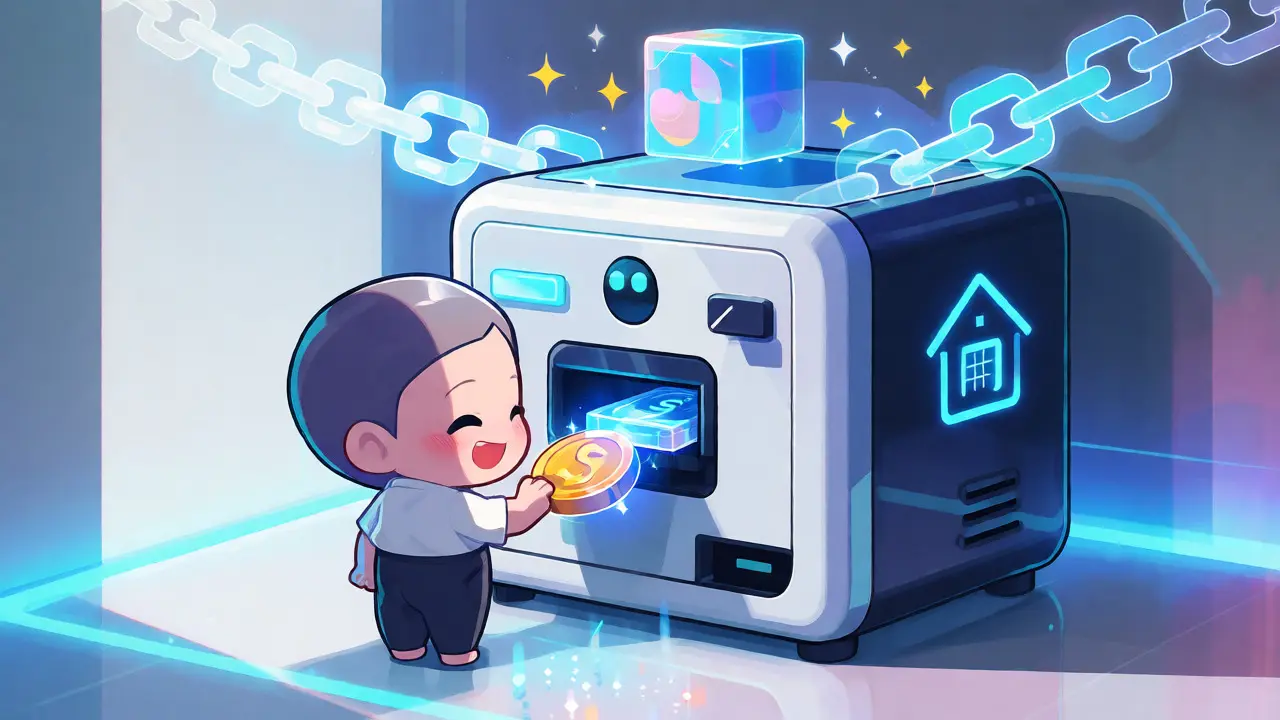
Smart contracts are the engine driving this efficiency. They are self-executing agreements where the terms are written directly into lines of code. Think of them as vending machines: you put in the coin (payment), and the machine automatically gives you the product (ownership transfer) when conditions are met. No attendant needed. For example, a smart contract can be programmed to release funds from escrow to the seller only after the digital title transfer is confirmed on the blockchain. This automation removes the need for manual verification steps that typically delay closings by weeks.
Tokenization: Breaking Down Ownership Barriers
One of the most exciting applications isn’t just selling whole houses faster; it’s about splitting them up. Property tokenization converts rights to an asset into a digital token on a blockchain. This allows for fractional ownership. Instead of needing $500,000 to buy a rental apartment, you might buy tokens representing shares in that property for as little as $50.
Platforms like RealT have pioneered this model. Users can invest in US-based rental properties, receive daily rent payouts via stablecoins, and trade their tokens on secondary markets. This liquidity was previously impossible in real estate. You couldn’t sell "1% of your kitchen" easily before; now, you can sell 1% of your investment property instantly to another investor globally.
| Feature | Traditional Method | Blockchain Method |
|---|---|---|
| Settlement Time | 30-60 days | Minutes to Days |
| Intermediaries | Title Co., Escrow, Bank, Lawyer | Smart Contract Code |
| Accessibility | High Capital Required | Fractional ($50+) |
| Record Security | Vulnerable to Human Error/Fraud | Immutable Cryptographic Ledger |
| Cross-Border Fees | High (Wire fees + FX spreads) | Low (Network gas fees) |
The Role of Major Platforms and Banks
This isn’t just a startup phenomenon anymore. Legacy financial giants are jumping in. J.P. Morgan, through its Kinexys platform, has demonstrated how blockchain can settle cross-border payments in minutes rather than the two days typical for SWIFT transfers. While they haven’t fully replaced legal deeds yet, they are proving that the settlement layer-the movement of money-can be vastly improved.
On the specialized side, companies like Propy are building end-to-end platforms that handle everything from listing to closing using Ethereum-based infrastructure. Propy allows users to sign contracts digitally and pay in cryptocurrency, effectively bypassing some traditional banking bottlenecks. These platforms are currently niche, handling less than 1% of global transactions, but their year-over-year growth exceeds 150%, signaling strong momentum.
Regulatory Hurdles and Legal Recognition
Here is the catch: technology moves faster than law. Just because you have a digital token doesn’t mean the local government recognizes it as legal proof of ownership. In many places, including parts of the US and Europe, you still need a paper deed filed with the county recorder. Blockchain serves as a supplementary record or a settlement tool, but rarely replaces the legal title itself entirely.
Countries like Estonia and Singapore are ahead of the curve, having established frameworks that recognize digital signatures and blockchain records more readily. However, in other jurisdictions, investors face uncertainty. If a smart contract executes but the local land registry hasn’t updated its database, who actually owns the property? This "oracle problem"-bridging the digital world with physical legal systems-is the biggest barrier to mass adoption today.
Getting Started: What Do You Need?
If you want to dip your toes into blockchain real estate, you don’t need to be a coder. Here’s a realistic path for beginners:
- Create a Crypto Wallet: Most platforms require a Web3 wallet like MetaMask. This takes about 15 minutes. Keep your seed phrase offline and safe.
- Complete KYC Verification: Unlike anonymous crypto trading, real estate requires identity checks. Expect to upload ID and proof of address.
- Fund Your Account: You’ll likely need stablecoins (like USDC) or ETH. Stablecoins reduce volatility risk since property prices are pegged to fiat currencies.
- Research the Platform: Look for audits. Has the smart contract been reviewed by security firms? Does the platform hold the actual legal deed in a Special Purpose Vehicle (SPV)?
For those interested in direct purchases rather than fractional investing, expect a steeper learning curve. Interacting with decentralized exchanges and understanding gas fees (transaction costs on the Ethereum network) requires a bit more technical comfort.
Future Outlook: Where Is This Heading?
We are currently in the experimental phase. By 2030, analysts predict that blockchain will become standard for international investments and high-frequency trading assets. Artificial Intelligence is also entering the mix, with AI agents potentially automating property valuations within smart contracts, adjusting sale prices dynamically based on market data.
However, don’t expect your next local home purchase to be purely on-chain tomorrow. Complex commercial deals involving zoning laws, environmental assessments, and multiple stakeholders will likely remain hybrid models for years. The immediate win is transparency and speed for simpler transactions and fractional investments.
Is blockchain real estate safe from fraud?
Yes, the ledger itself is highly secure against tampering. Once a transaction is recorded, it is nearly impossible to alter without consensus from the network. However, user error remains a risk. If you lose your private keys or send funds to the wrong address, there is no customer support hotline to reverse the transaction. Additionally, the safety of the underlying property depends on the legal structure of the tokenizing entity, not just the code.
Can I buy a house with Bitcoin?
Technically, yes, many sellers accept cryptocurrency. However, most prefer stablecoins (cryptocurrencies pegged to the dollar) to avoid price volatility during the transaction period. Some platforms allow you to convert Bitcoin to stablecoins instantly within the smart contract workflow, ensuring the seller receives a predictable amount.
What are the tax implications of tokenized real estate?
Tax laws vary significantly by country. Generally, profits from selling tokens are treated similarly to capital gains from selling stocks or property. Rent distributions may be taxed as income. Because regulations are still evolving, it is crucial to consult a tax professional familiar with both real estate and cryptocurrency in your specific jurisdiction.
Do I need to know coding to use these platforms?
No. User interfaces for platforms like RealT or Propy are designed to look like traditional apps. You click buttons to buy, sell, or view dividends. Coding knowledge is only necessary if you are developing your own smart contracts or integrating custom solutions into enterprise workflows.
Why aren't all real estate deals on blockchain yet?
The main barriers are regulatory recognition and legacy system integration. Many local governments do not legally recognize blockchain entries as official titles. Furthermore, the existing MLS (Multiple Listing Service) systems used by agents are not compatible with blockchain databases, creating friction for real estate professionals who rely on these tools.